
ESG in a supply chain is not a report. It is a set of claims about how goods were made, each of which has to be traceable to a document, a site and a date. The report is the last step; the work is the record behind it.
That distinction matters because most supply chain ESG programmes fail in the same place: not at the policy, but at the evidence. A buyer publishes a supplier code, the code is acknowledged, and two years later nobody can say which site produced which batch, or who checked. The commitment existed; the record did not.
This is written for the buying side — the team that has to answer a customer questionnaire, a bank, an investor or a border authority, and has to answer it about suppliers it does not own.
The four things ESG actually asks of a sourcing function
Strip away the frameworks and the requests reduce to four. Each one lands on a different part of the operation, and each fails for a different reason.
Where the goods were made. Not the trading address, not the showroom — the production site, with a name and an address that can be visited. This fails because supply chains are layered, and the entity that invoices is often not the entity that produces.
Under what conditions. Working hours, wage records, safety, and the age of the workforce. This fails because the evidence sits with the supplier, is produced monthly, and is rarely collected in a form that can be checked later.
With what materials. Composition and origin, including recycled content and any restricted substance. This fails because material substitution happens quietly at the mill, and the buyer learns about it in a test report rather than in a conversation.
With what footprint. Energy, water, and emissions attributable to the order. This fails because most suppliers can state a company-level number and cannot state an order-level one.
A programme that addresses only the first two is a labour compliance programme with an environmental heading.
Why the data is usually missing
The instinct is to blame the supplier. More often the cause is the buying process.
Purchase orders are placed against a product, not against a site. Invoicing runs through a trading entity. Samples are approved by email. Changes are agreed by phone. None of that leaves a record that can be joined up later, so when the questionnaire arrives, the answers are reconstructed from memory by people who were not there.
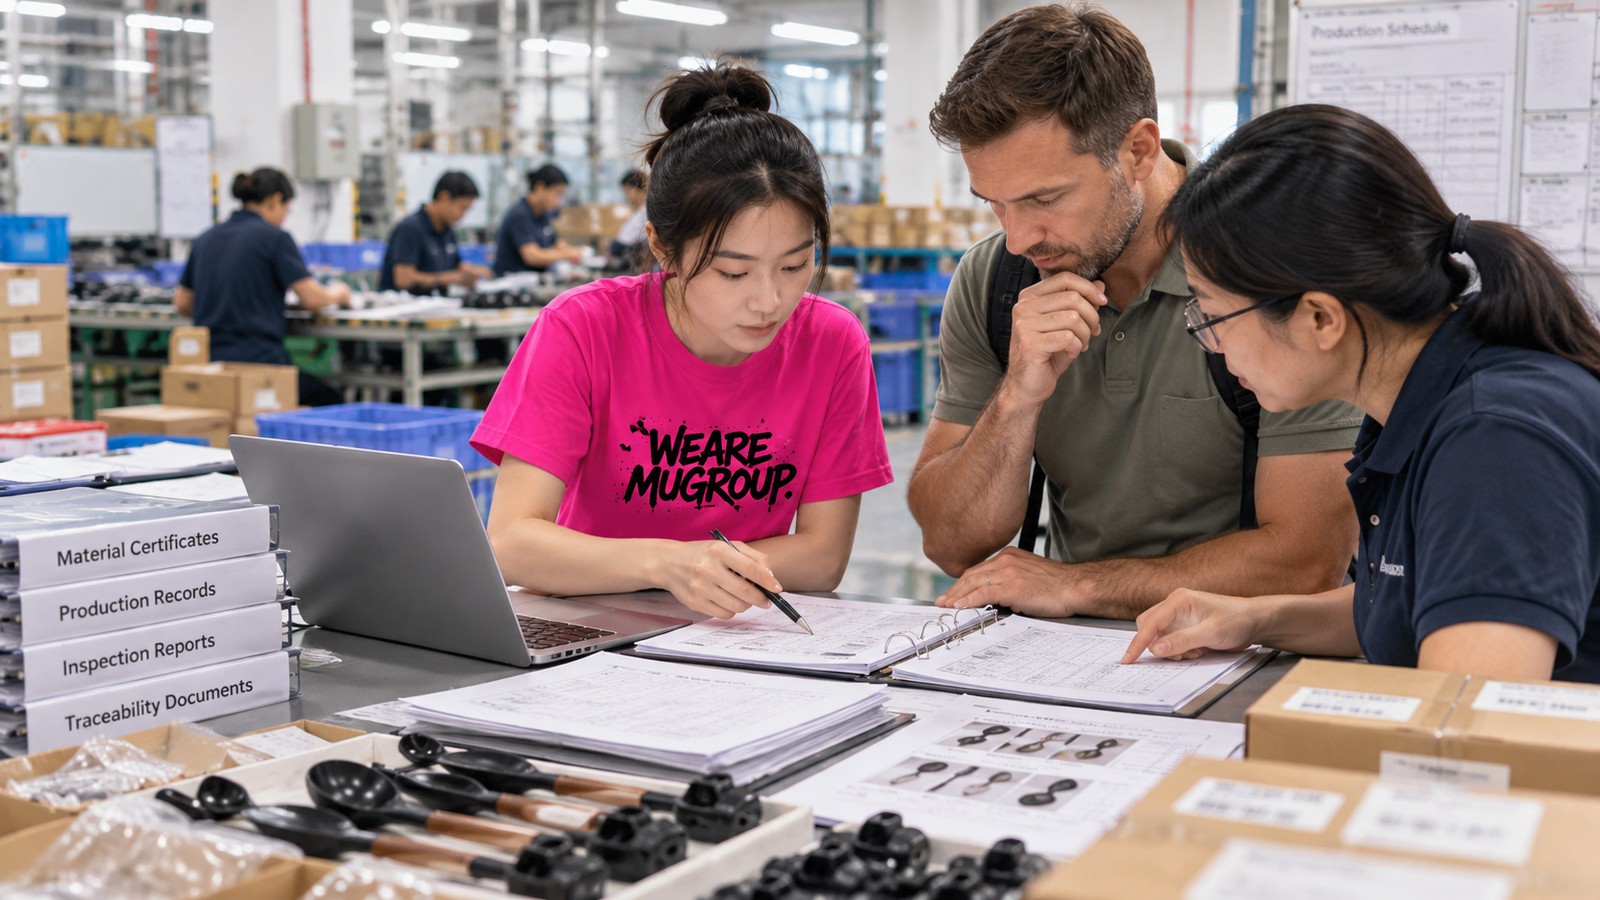
Three habits close most of the gap, and none of them require new software.
Record the production site on the purchase order, not just the supplier name. Make the approved sample a written document with photographs and a date, rather than a physical object in a drawer. And keep the change log — every substitution, who approved it, and when — because the change log is what turns a claim into a traceable fact.
Screening a supplier for substance, not for paperwork
Certificates are easy to obtain and easy to misread. They are also frequently held by a different legal entity than the one producing your order.
Five questions separate a supplier with a system from a supplier with a folder of documents.
-
Which site will produce this order, and is that the site named on the certificate?
-
Who records working hours, and can I see the record for a recent month rather than a summary?
-
When was the last time a customer or a third party audited this site, and what were the findings?
-
If a material is substituted, who approves it, and where is that approval recorded?
-
Which of these answers would change if the order doubled?
The last question is the useful one. A supplier with a real system answers it; a supplier with a document set changes the subject.
Disclosure and performance are not the same thing
A growing share of ESG content is disclosure: a number published, a target announced, a rating obtained. Disclosure is necessary and it is not evidence of performance.
Two practical tests. First, does the number have a boundary? An emissions figure without a stated scope and boundary cannot be compared with anything, including last year’s figure. Second, is the number produced at the level the buyer needs — company, site, or order? A company-level figure cannot support an order-level claim, and buyers who pass one up the chain are exposed when the next party asks for the basis.
The same applies to targets. A target with a baseline year, a scope and an interim milestone is a plan. A target with an adjective is a press release.
What changes when the buyer is regulated
Regulated buyers — those selling into markets with border carbon mechanisms, mandatory due diligence or extended producer responsibility — face a different problem from voluntary programmes: the claim has to survive an external check, and the buyer carries the consequence, not the supplier.
Three things change in practice.
The evidence requirement moves from annual to transactional. A site audit every two years does not answer a question about a specific shipment.
The chain of custody has to be documented between parties that do not share systems. This is where consolidation becomes an ESG problem: when four suppliers feed one container, the material and site record has to follow the carton, not the order.
And the buyer needs the ability to stop. A programme without an escalation path — what happens when a site fails, who decides, how the goods are held — is a reporting exercise rather than a control.
Building a record that survives being checked
The test of an ESG record is not whether it satisfies today’s questionnaire. It is whether a different person, eighteen months later, can reconstruct what happened without asking the original team.
That points to four properties. The record should be attached to the transaction rather than to the supplier file. It should be dated at the point of the event, not at the point of reporting. It should name the site, not only the company. And it should be readable by someone outside the sourcing team, because the people who will be asked are rarely the people who collected it.
None of this requires a platform. It requires deciding, before the order is placed, which four facts will be recorded and who is accountable for each.
Where MU Group sits
MU Group works as a sourcing and supply chain partner rather than a manufacturer, which puts the group on the buying side of this problem: the work is to make the record exist at the point where the order is placed, and to keep it attached to the goods as they move.
In practice that means procurement management that records the production site, quality control that documents what was checked and against which standard, packaging and labelling coordination that keeps the artwork and the specification traceable, and logistics coordination that keeps the carton-level record intact through consolidation.
How much of that is available for a given supply chain depends on the category, the existing supplier relationships and the markets being served, and it is better established in a conversation than assumed. The wider service scope is described under what MU Group does.
Frequently asked questions
Is ESG only relevant to large buyers?
No, but the trigger is usually external: a customer questionnaire, a bank, an insurer or a marketplace requirement. Smaller buyers tend to meet the requirement because someone downstream asked, not because they set a policy.
Do we need certifications to answer an ESG questionnaire?
Certifications answer some questions and none of the traceability ones. What the questionnaire usually wants is a site name, a date and a document — which is a records problem, not a certification problem.
How far down the chain does a buyer have to go?
At least to the site that performs the final production step, and further where a material or process carries the main risk. The practical limit is the point where the buyer can no longer obtain a document.
Can this be handled after the order is placed?
Partly. Site identity and material specification can be recorded late at some cost; labour records and change logs cannot be reconstructed credibly after the fact.
Does consolidation make ESG harder?
It makes traceability harder and transport footprint easier. The record has to follow the carton through the consolidation point, which is a process question rather than a data question.
Buyers who are being asked these questions for the first time can start with the scope of the order rather than with a policy document.